El mundo cambió. Las normas fiscales deben cambiar con él.
Declaración de ICRICT sobre la Convención Marco de las Naciones Unidas para la Cooperación Fiscal Internacional — Bangkok, octubre de 2026 Al margen de las Reuniones Anuales del FMI y del Banco Mundial en Bangkok, ICRICT, la Comisión Internacional sobre Tributación del Capital, lanzó un llamado para que todos los países ocupen su lugar en […]
The World Changed. The Tax Rules Must Change with It.
ICRICT statement on the UN Framework Convention on International Tax Cooperation — Bangkok, October 2026 On the sidelines of the IMF and World Bank Annual Meetings in Bangkok, ICRICT, the International Capital Tax Commission, launched a call for all countries to take their seat at the table when negotiations on the UN Framework Convention on […]
Taxing Companies Profiting From the US-Israel War Against Iran
April, 2026.The ongoing US-Israel war against Iran and the wider destabilisation of global energy markets have triggered an extraordinary surge in oil, gas and fertiliser prices — a surge that disproportionately hurts ordinary workers, farmers, and fossil fuel importing nations, while a small group of large corporations and state producers accumulate windfall profits at their […]
Gravar a las Empresas que se Benefician de la Guerra de Estados Unidos-Israel contra Irán
Abril, 2026. La guerra en curso de Estados Unidos e Israel contra Irán y la desestabilización más amplia de los mercados energéticos mundiales ha desencadenado un aumento extraordinario en los precios del petróleo, el gas y los fertilizantes, aumento que perjudica desproporcionadamente a los trabajadores, los agricultores y las nacionesimportadoras de combustibles fósiles, mientras un […]
ICRICT statement on the UN negotiations for a Framework Convention on International TaxCooperation and its two early protocols.
Nairobi, 10 November 2025
The Us Threat To Global Tax Reform: A Proposal For Protecting Multilateralism

ICRICT Submission on the Draft Issue Note of Workstream II: Reforming Cross-Border Service Taxation in a Globalized Digital Economy
This submission addresses the urgent need to reform the taxation of cross-border services in a globalized and digitalized economy. ICRICT calls for abandoning outdated rules—such as physical presence requirements and the arm’s length principle—and adopting a new framework based on unitary taxation and formulary apportionment. The Commission also recommends establishing a nexus rule based on […]
ICRICT Submission on the Draft Issue Note of Workstream I: Towards an Inclusive and Equitable UN Framework Convention on International Tax Cooperation
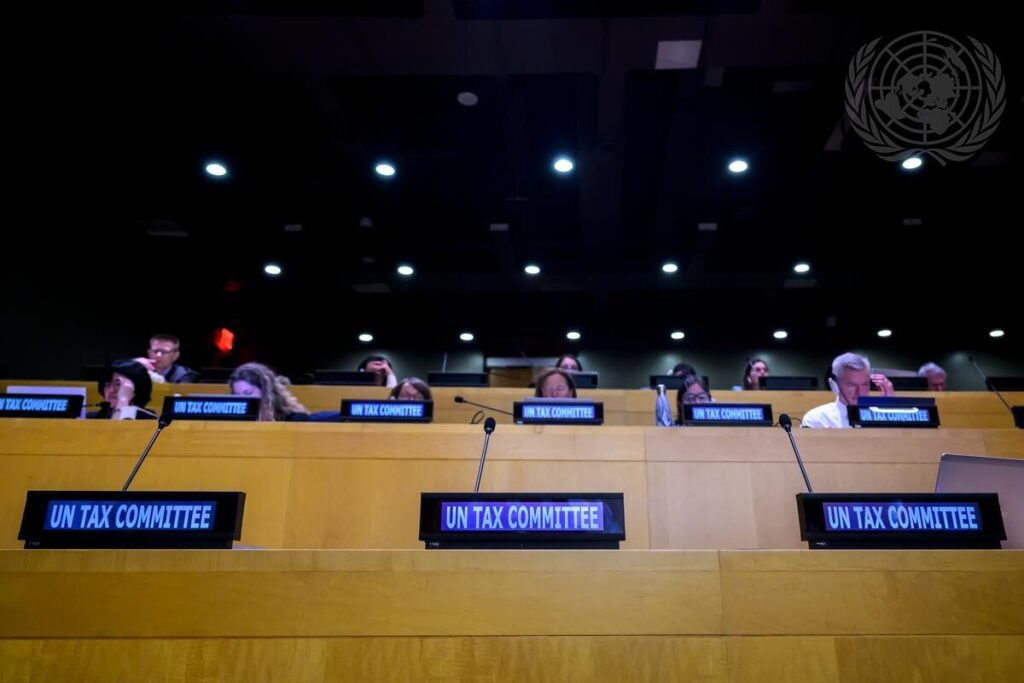
This submission outlines ICRICT’s recommendations on the scope and content of the UN Framework Convention on International Tax Cooperation. It calls for replacing outdated rules—such as the arm’s length principle and residence-based taxation—with a unitary system that allocates taxing rights based on real economic activity. ICRICT also rejects mandatory arbitration, urging instead for simpler rules […]
Principles and Protocols for a UN Framework Convention on International Tax Cooperation
This document outlines ICRICT’s recommendations for the negotiation of a UN tax convention, emphasizing on the principles needed to create a fairer global tax system and possible prioritization of protocols for the intergovernmental negotiating committee to work on at an early stage. ICRICT calls for commitments to unitary taxation of multinational profits, effective taxation of high-net-worth individuals, and […]
Protocol on Tax-Related Illicit Financial Flows (IFFs)
Illicit financial flows — from tax evasion and avoidance of high-net-worth individuals and multinational enterprises — undermine revenues and development, especially in low-income countries. ICRICT calls for a UN protocol to strengthen international cooperation and address the problems in existent international tax architecture to effectively tackle international tax evasion and avoidance. Recommendations include increasing tax […]